

Top livery businesses we insure
Recommended livery insurance policies
These insurance products help livery businesses pay for auto accidents, lawsuits, data breaches, and theft. Some policies may be required by law.

General liability insurance
This policy covers the most common lawsuits brought by people outside your business, such as a customer who slips and gets a concussion at your livery company's office.
- Customer bodily injuries
- Damaged customer property
- Accidental copyright infringement

Business owner's policy
A BOP is a cost-effective way for black car services and other livery businesses to buy general liability coverage and commercial property insurance together.
- Accidents that harm customers
- Business property damage
- Business interruption insurance

Commercial auto insurance
This policy covers financial losses from accidents involving your livery business's vehicles. Each state has its own requirements for auto liability insurance.
- Injuries caused by your vehicles
- Property damaged by your vehicles
- Stolen or vandalized vehicles

Workers' compensation insurance
Most states require workers' comp for livery companies that have employees. It also covers work-related medical costs for sole proprietors, which health insurance can deny.
- Employee medical expenses
- Disability benefits
- Workplace injury lawsuits

Cyber insurance
This policy helps limousine services and other livery businesses recover from a data breach or cyberattack. It's recommended for any business that stores customer information.
- Data breach investigations
- Fraud monitoring services
- Customer notification costs

Errors and omissions insurance
E&O insurance covers legal defense costs when a livery business is sued for a missed appointment or other claim of professional negligence. It's also called professional liability insurance.
- Late or undelivered rides
- Breach of contract
- Failure to meet expectations
Does my livery business need commercial auto insurance?
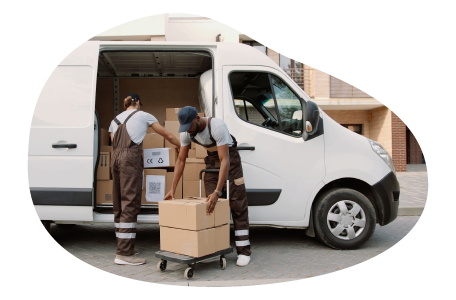
Livery businesses that own vehicles are required to carry commercial auto insurance. The specific car insurance you need depends on:
- Where your business operates
- Whether you transport people or cargo
- Whether you tow vehicles or other items
- Whether you use trucks or heavy equipment
The Federal Motor Carrier Safety Administration (FMCSA) has additional requirements for motor carriers, especially for truckers that cross state lines.
Check the laws in your state to see when coverage is required.
How much does livery insurance cost?
Small livery companies with low risks don't have to pay a lot for business insurance.
Insurance companies look at several factors when determining your premiums, including:
- Type of business, such as airport shuttle service, rideshare service, or taxi service
- Value of business property
- Number of employees
- Employee driving records
- Type of coverage (e.g., basic auto insurance vs. physical damage coverage)
- Policy limits and deductibles
- Claims history
How do I get commercial livery insurance?
It’s easy to find insurance for your livery business with Insureon. Whether you offer limos, charter buses, or taxis, you’ll need to provide some basic information about your business, such as your annual revenue and payroll.
You can buy a policy online and get a certificate of insurance (COI) that shows proof of insurance in three easy steps:
- Fill out our free online application.
- Compare free quotes and choose a policy.
- Pay for your policy and download a certificate.
Insureon's licensed insurance agents work with top-rated U.S. providers to find the best livery coverage for your business. Gain peace of mind with policies that match your specific risks and requirements.
Verified business insurance reviews
Hear from customers like you who purchased small business insurance.
FAQs about insurance for livery businesses
Review answers to common questions about taxi insurance, limo insurance, rideshare insurance, and other types of livery insurance.
How do livery insurance requirements vary by state?
There are a few instances where state laws will determine the insurance coverage you need for your livery business. For example:
- You need workers' compensation for your employees. Each state has its own laws for workers' compensation insurance. For example, California and New York both require this coverage for all employees, even those who work part-time.
- You need a commercial auto policy for your vehicles. Almost every state requires commercial auto insurance for vehicles owned by your business. Some states have unique laws, such as New Jersey which offers a choice between basic or standard auto policies.
- You may need for-hire livery insurance. States, cities, and other municipalities often require auto liability insurance and surety bonds for services that transport passengers for a fee. This coverage is also called for-hire insurance.
Your state might have additional requirements beyond insurance. You usually need a business license, and if you operate your business under a name other than your own, you'll need to register your "doing business as" or DBA name as well.
Do self-employed business owners need livery vehicle insurance?
Sole proprietors, independent contractors, and other self-employed individuals are subject to the same laws and liabilities as bigger businesses. That means you'll need a commercial auto insurance policy if your vehicle is owned by your business, or hired and non-owned auto insurance (HNOA) if you drive a personal, leased, or rented vehicle for work.
Your clients might also require you to carry insurance. For example, the driver of a non-emergency medical transport (NEMT) might need liability coverage to work with a specific healthcare facility.
Remember, livery drivers, including drivers for Uber and Lyft, can’t depend on their personal auto policy. It won't cover work-related driving, which could leave you on the hook for expensive legal bills if you're involved in an accident.
What other types of insurance policies should livery business owners consider?
In addition to the policies mentioned above, livery business owners often buy the following:
- Commercial umbrella insurance: An umbrella policy boosts the coverage of general liability, commercial auto, and employer's liability insurance once they reach their limit on a claim. You may need this coverage to meet a client's request for higher liability limits.
- Commercial property insurance: This policy helps you recover financially from theft, vandalism, fires, and similar incidents. You can buy it bundled with general liability insurance in a business owner's policy.
- Garage liability insurance: Businesses that store or service vehicles need this type of coverage to protect against customer injuries that happen in your garage. It provides the same coverage as a general liability policy for the high-risk setting of a garage.
Get free livery insurance quotes
Read our blog posts

Although personal auto and commercial auto insurance are both types of vehicle coverage, they protect drivers in different ways. Understanding what your personal and commercial liability insurance...

Want free expert advice right in your inbox?
By entering your email address and subscribing, you agree to our Terms of Use and Privacy Policy